2026 Capital Gains Tax Adjustments: Impact on Institutional Liquidity
Advertisements
The 2026 capital gains tax policy adjustments are poised to significantly reshape institutional liquidity, influencing investment decisions, asset allocation, and overall market stability across the United States.
The Impact of 2026 Capital Gains Tax Policy Adjustments on Institutional Liquidity
The financial landscape is ever-evolving, and few factors exert as much influence as tax policy. As we approach 2026, the anticipated adjustments to 2026 capital gains tax policies are generating considerable discussion and strategic planning within institutional investment circles. Understanding these changes is crucial for predicting market behavior and adapting investment strategies.
Understanding the Proposed 2026 Capital Gains Tax Reforms
The impending 2026 capital gains tax reforms represent a significant shift in how investment profits will be treated, directly affecting financial institutions and their operational liquidity. These proposed changes aim to recalibrate the balance between government revenue and investment incentives, potentially leading to widespread implications across various asset classes and market participants. Investors, from large pension funds to hedge funds, are meticulously analyzing these proposals to gauge their future financial standing and strategic maneuvers.
Historically, capital gains taxation has been a critical lever for economic policy, influencing everything from individual savings to corporate investment decisions. The 2026 adjustments are not merely incremental; they are designed to address perceived inequities and fund new government initiatives. This necessitates a comprehensive understanding of the specifics of these reforms to anticipate their ripple effects throughout the financial ecosystem. Institutional investors, with their vast portfolios and complex structures, are particularly vulnerable to these changes due to the sheer volume and value of their holdings.
Key Aspects of the Proposed Changes
Several facets of the 2026 capital gains tax adjustments stand out as particularly impactful for institutional liquidity. These include potential changes to the tax rates themselves, alterations to holding period definitions, and possible modifications to tax exemptions and deferral mechanisms. Each of these components, individually and collectively, could trigger substantial shifts in investment behavior and capital allocation.
- Increased Tax Rates: Proposals often include raising the top marginal rates for long-term capital gains, aligning them more closely with ordinary income rates for high-income earners.
- Holding Period Modifications: Changes to what constitutes a 'long-term' capital gain could incentivize or disincentivize shorter-term trading strategies.
- Elimination of Step-Up in Basis: This controversial proposal would eliminate the tax benefit of asset appreciation upon inheritance, significantly impacting estate planning and generational wealth transfer.
- New Surcharge Taxes: Some proposals suggest additional surcharges on very high capital gains, further increasing the tax burden for large institutional investors.
The cumulative effect of these proposed changes could redefine the profitability calculus for many institutional investment strategies. For example, a higher tax rate on long-term gains might reduce the appeal of buy-and-hold strategies, while the elimination of the step-up in basis could prompt a re-evaluation of long-term asset accumulation for endowments and family offices.
Understanding the nuances of these proposed reforms is the first step for institutions to effectively navigate the evolving tax landscape. The scale of these adjustments demands proactive planning and a deep analysis of their potential ramifications on portfolio performance and liquidity management.
Direct Impact on Institutional Liquidity and Capital Flow
The direct consequences of the 2026 capital gains tax adjustments on institutional liquidity are multifaceted and significant. Liquidity, the ease with which an asset can be converted into cash without affecting its market price, is paramount for institutions managing large sums of capital. Any policy change that impacts the net proceeds from asset sales will inherently affect their ability to meet obligations, seize opportunities, and manage risk.
Higher capital gains taxes mean that a larger portion of realized gains will be remitted to the government, leaving less capital available for reinvestment or distribution. This reduction in available capital can constrain liquidity, forcing institutions to adjust their investment horizons, re-evaluate their risk appetite, and potentially alter their asset allocation strategies. For instance, a pension fund might find itself with less free cash flow to meet beneficiary payouts if a significant portion of its realized gains is siphoned off by increased taxes.
Behavioral Shifts in Investment Decisions
The anticipation of higher taxes can lead to preemptive actions by institutional investors. Before the new policies take effect, there might be a surge in asset sales to realize gains under the current, more favorable tax regime. This 'pull-forward' of taxable events could create temporary market volatility, particularly in highly appreciated assets. Conversely, once the new rules are in place, institutions might become more reluctant to sell assets, leading to a 'lock-in' effect where investors hold onto appreciated assets to defer tax liabilities.
- Increased Pre-emptive Selling: Institutions may accelerate asset sales to realize gains before higher rates become effective, potentially causing short-term market dips.
- Reduced Post-Tax Reinvestment: Lower net proceeds from sales mean less capital available for new investments, impacting market depth and funding for new ventures.
- Shift to Tax-Efficient Structures: Greater emphasis on tax-advantaged investment vehicles, such as municipal bonds or certain private equity structures, could emerge.
- Longer Holding Periods: A 'lock-in' effect might occur, where institutions defer selling appreciated assets to avoid higher immediate tax burdens, potentially reducing market velocity.
These behavioral shifts are not merely theoretical; they have tangible consequences for market functioning. A 'lock-in' effect can reduce market liquidity by decreasing the supply of available assets, potentially exacerbating price volatility during periods of high demand. Furthermore, the redirection of capital towards more tax-efficient structures could distort market prices and resource allocation, favoring certain sectors or asset classes over others.
The direct impact on institutional liquidity is a critical concern, influencing everything from daily operational cash management to long-term strategic planning. Institutions must model various tax scenarios and develop robust contingency plans to maintain adequate liquidity levels under the new regime.
Indirect Market Implications and Asset Reallocation
Beyond the direct effects on institutional balance sheets, the 2026 capital gains tax adjustments are expected to trigger a wave of indirect market implications, primarily manifesting as significant asset reallocation. Institutional investors, driven by fiduciary duties and the pursuit of optimal risk-adjusted returns, will inevitably adjust their portfolios to mitigate tax burdens and capitalize on new opportunities. This reallocation can have profound effects on market valuations, sector performance, and the overall efficiency of capital markets.
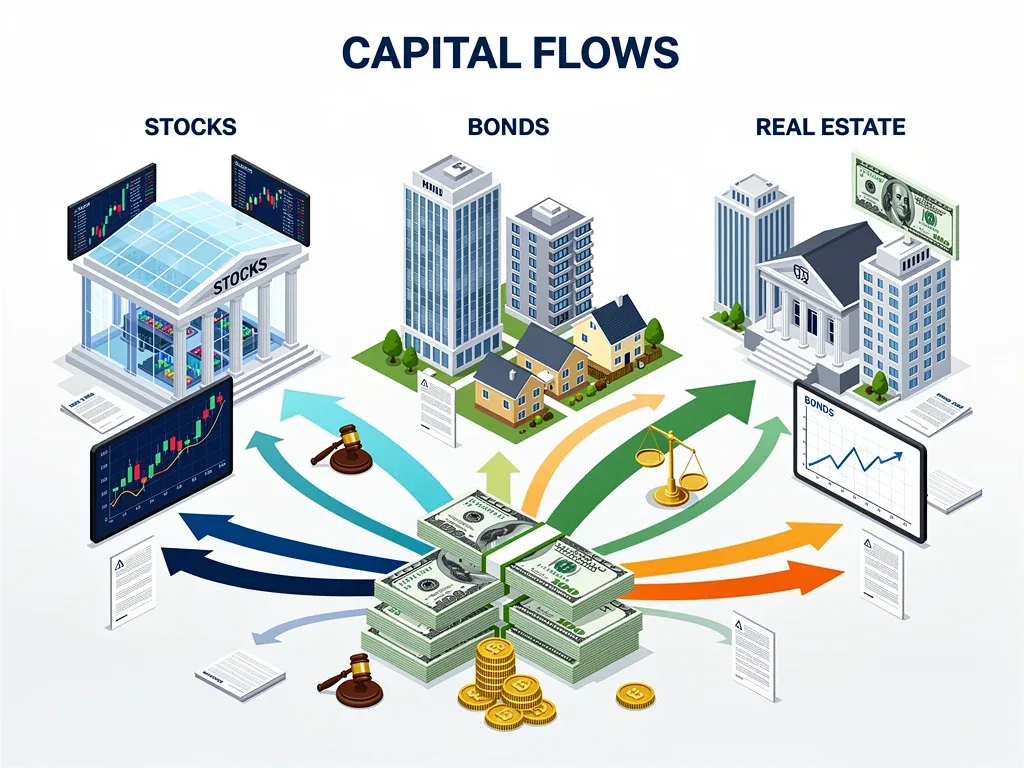
One of the most anticipated indirect consequences is a potential shift away from publicly traded equities, which are highly susceptible to capital gains taxation, towards alternative investments or private markets. Assets like private equity, venture capital, and real estate, while still subject to capital gains, often offer different tax deferral mechanisms or valuation methodologies that might become more attractive under a stricter tax regime. This shift could lead to a re-rating of public market assets and a greater emphasis on illiquid investments, altering the risk profile of institutional portfolios.
Sectoral Winners and Losers
The rebalancing of institutional portfolios will not be uniform across all sectors. Certain industries or asset classes might inadvertently benefit, while others face headwinds. For example, sectors that historically rely on long-term capital appreciation, such as technology and growth stocks, might see reduced institutional interest if the after-tax returns diminish significantly. Conversely, dividend-paying stocks or assets with more stable, income-generating profiles could become more appealing.
- Increased Demand for Income-Generating Assets: Bonds, preferred stocks, and real estate investment trusts (REITs) offering consistent income streams might see increased institutional allocation.
- Growth in Private Markets: Private equity, private debt, and venture capital could attract more capital as institutions seek alternative avenues for tax-efficient growth and longer investment horizons.
- Impact on Public Equity Valuations: A sustained shift away from public equities could depress valuations, particularly for companies heavily reliant on capital appreciation.
- Emergence of Tax-Optimized Products: Financial innovators will likely develop new investment products and strategies specifically designed to minimize capital gains tax liabilities for institutions.
The reallocation of capital is a dynamic process, and its full extent will depend on the final details of the tax legislation and how institutions interpret and respond to it. However, the expectation is that there will be a discernible movement of capital, creating both challenges and opportunities for different segments of the financial market.
Understanding these indirect market implications is crucial for institutions to not only protect their existing capital but also to position themselves strategically for future growth in a tax-adjusted environment.
Strategic Responses from Institutional Investors
In anticipation of the 2026 capital gains tax adjustments, institutional investors are not remaining passive; rather, they are actively developing and implementing sophisticated strategic responses. These strategies aim to mitigate the adverse effects of higher taxes on liquidity and returns, while also seeking to identify and exploit new opportunities presented by the altered tax landscape. The complexity of these adjustments demands a multi-pronged approach, encompassing portfolio restructuring, operational efficiency, and engagement with policymakers.
One primary strategic response involves a rigorous re-evaluation of portfolio construction. Institutions are conducting comprehensive tax-impact analyses on their existing holdings, identifying assets that will be most affected by the new rules. This often leads to tactical selling ahead of the implementation date, or a strategic shift towards asset classes that offer more favorable tax treatment or deferral options. The goal is to optimize after-tax returns, ensuring that the institution can continue to meet its financial objectives and obligations.
Adapting Investment Methodologies
Beyond simple asset reallocation, institutions are also refining their investment methodologies. This includes a greater emphasis on tax-loss harvesting, where losses are strategically realized to offset capital gains, and a deeper dive into tax-efficient wrappers and structures. For example, the use of exchange-traded funds (ETFs) with specific tax advantages or separately managed accounts (SMAs) that allow for greater tax customization might become more prevalent.
- Enhanced Tax-Loss Harvesting: More proactive and systematic realization of losses to offset gains, improving after-tax performance.
- Increased Use of Tax-Advantaged Vehicles: Greater adoption of investment structures designed to minimize tax liabilities, such as certain types of trusts or specific fund structures.
- Focus on Long-Term, Income-Generating Investments: A strategic pivot towards assets that provide consistent income rather than solely relying on capital appreciation, potentially reducing immediate tax burdens.
- Sophisticated Tax Modeling: Investment in advanced analytical tools and expertise to accurately forecast tax liabilities and optimize portfolio decisions under various tax scenarios.
Furthermore, many institutions are engaging with policymakers and industry groups to advocate for modifications to the proposed tax changes or to seek clarification on ambiguous aspects of the legislation. This proactive engagement is critical for shaping the final form of the regulations and ensuring that institutional concerns are adequately addressed.
The strategic responses from institutional investors highlight their adaptability and commitment to protecting and growing their capital in a challenging regulatory environment. These strategies are not static; they will continue to evolve as the tax landscape clarifies and market reactions unfold.
Regulatory Compliance and Operational Challenges
The advent of the 2026 capital gains tax adjustments introduces a complex web of regulatory compliance and operational challenges for institutional investors. Navigating these new rules requires not only a deep understanding of tax law but also significant operational adjustments to reporting, accounting, and internal processes. Failure to comply can result in severe penalties, while inefficient adaptation can erode profitability and competitive advantage.
Institutions must invest heavily in upgrading their internal systems and training their personnel to accurately track, calculate, and report capital gains under the new regime. This includes ensuring that their portfolio management software, accounting systems, and tax reporting tools are fully capable of handling the revised definitions, rates, and exemptions. The complexity often increases with the diversity of assets held and the international nature of some investment portfolios.
Ensuring Accurate Reporting and Avoiding Penalties
One of the primary operational challenges is the need for meticulous record-keeping and precise calculation of capital gains and losses. Any changes to holding periods, basis adjustments, or tax rates necessitate a complete overhaul of how these figures are derived and reported. Institutions must ensure that their internal controls are robust enough to prevent errors that could lead to audits, fines, or reputational damage.
- System Upgrades: Investment in new software or modifications to existing systems to accommodate updated tax calculation methodologies and reporting requirements.
- Staff Training: Comprehensive training programs for finance, accounting, and portfolio management teams on the specifics of the new tax laws and their operational implications.
- Enhanced Data Management: Improved processes for collecting, storing, and accessing granular data related to asset purchases, sales, and holding periods.
- Internal Audit and Compliance Reviews: Regular internal checks and third-party audits to ensure adherence to all new tax regulations and reporting standards.
The sheer volume of transactions processed by large institutional investors means that even minor changes in tax rules can translate into substantial operational burdens. The challenge is not just about understanding the law, but about embedding that understanding into the daily workflow of a complex financial organization. Moreover, the need to comply with potentially varying state-level capital gains tax regulations further complicates the compliance landscape.
Effectively managing regulatory compliance and operational challenges will be a critical differentiator for institutional investors in the post-2026 tax environment. Those that can adapt swiftly and efficiently will be better positioned to maintain liquidity and optimize returns.
Long-Term Economic and Market Stability
The 2026 capital gains tax adjustments, while primarily focused on revenue generation and wealth redistribution, also carry significant implications for long-term economic and market stability. The way institutional investors respond to these changes can either bolster or undermine confidence in the financial system, affecting everything from capital formation to global competitiveness. Understanding these broader consequences is essential for policymakers and market participants alike.
One potential long-term effect is on capital formation. If higher capital gains taxes significantly reduce the after-tax returns on investment, there could be a dampening effect on the incentive to save and invest, particularly in riskier, growth-oriented ventures. This could slow down innovation, reduce job creation, and ultimately hinder economic growth. Institutions, as major allocators of capital, play a crucial role in directing funds towards productive uses, and any disincentive could have widespread repercussions.
Impact on Market Volatility and Efficiency
The behavioral shifts induced by the new tax regime could also affect market volatility and efficiency over the long term. A 'lock-in' effect, where investors are reluctant to sell appreciated assets, can reduce market liquidity and make prices less responsive to new information. This can lead to greater price swings and make it harder for new capital to flow into promising opportunities, thereby reducing market efficiency.
- Reduced Capital Formation: Higher taxes might disincentivize long-term investment, potentially slowing economic growth and innovation.
- Increased Market Volatility: Reduced liquidity from a 'lock-in' effect could lead to greater price fluctuations and less efficient price discovery.
- International Competitiveness: If the US capital gains tax rates become significantly higher than those in other major economies, it could lead to capital flight or reduced foreign investment.
- Redistribution of Wealth: While a policy goal, the extent to which capital gains taxes achieve equitable wealth distribution without stifling economic activity remains a critical long-term consideration.
Moreover, the international competitiveness of US capital markets could be affected. If the 2026 capital gains tax rates are perceived as significantly less favorable than those in other developed nations, institutional investors might increasingly look to deploy capital in jurisdictions with more attractive tax regimes. This could lead to a decline in foreign direct investment into the US and a potential outflow of domestic capital, impacting the nation's economic standing.
Ultimately, the long-term economic and market stability will depend on a delicate balance between the government's fiscal objectives and the need to maintain a vibrant, liquid, and attractive investment environment. Continuous monitoring and potential adjustments to these tax policies will be crucial to ensure sustainable growth.
Preparing for the Post-2026 Tax Landscape
As the implementation of the 2026 capital gains tax adjustments draws nearer, institutional investors are intensifying their preparations for the new tax landscape. This proactive approach is not just about compliance, but about positioning themselves strategically to thrive amidst the changes. Effective preparation involves a combination of forecasting, scenario planning, and a willingness to adapt investment philosophies.
A critical component of this preparation is the development of robust financial models that can simulate the impact of various tax scenarios on portfolio returns and liquidity. These models help institutions understand their potential tax liabilities, identify areas of vulnerability, and explore different investment strategies that could optimize after-tax performance. This analytical rigor is paramount for informed decision-making.
Key Preparatory Actions
Institutions are also focusing on enhancing their internal capabilities and external partnerships. This includes engaging with tax advisors, legal experts, and technology providers who specialize in tax compliance and optimization. The complexity of the new regulations often necessitates external expertise to ensure full compliance and to identify innovative solutions for managing tax burdens.
- Comprehensive Portfolio Review: An in-depth analysis of all current holdings to assess their susceptibility to the new tax rules and identify potential areas for restructuring.
- Scenario Planning and Stress Testing: Developing various tax scenarios and stress-testing portfolios to understand potential impacts on liquidity and returns.
- Engagement with Tax Experts: Consulting with specialized tax attorneys and advisors to interpret the new legislation and develop compliant, efficient strategies.
- Technology and Data Infrastructure Upgrades: Ensuring that all financial systems are capable of handling new tax calculations, reporting requirements, and data management needs.
Furthermore, institutions are educating their boards, investment committees, and client bases about the impending changes and their potential implications. Transparent communication is vital for managing expectations and maintaining trust, especially when adjustments to investment strategies or expected returns are necessary.
Preparing for the post-2026 tax landscape is an ongoing process that requires continuous vigilance and flexibility. Institutions that embrace these preparations will be better equipped to navigate the challenges and capitalize on the opportunities that arise from the evolving tax environment.
| Key Point | Brief Description |
|---|---|
| Higher Tax Rates | Increased capital gains tax rates reduce after-tax returns and available capital for reinvestment. |
| Behavioral Shifts | Anticipation of changes drives pre-emptive selling or a 'lock-in' effect, impacting market liquidity. |
| Asset Reallocation | Institutions shift capital towards tax-efficient assets and private markets, affecting public market valuations. |
| Operational Challenges | New rules demand system upgrades, staff training, and enhanced compliance to avoid penalties. |
Frequently Asked Questions About 2026 Capital Gains Tax
What are the main proposed changes to capital gains tax in 2026?▼The main proposed changes include potential increases in tax rates, modifications to holding period definitions for long-term gains, and the possible elimination of the step-up in basis for inherited assets. These adjustments aim to generate revenue and address wealth distribution concerns.
How will these changes affect institutional liquidity?▼Higher capital gains taxes will reduce the net proceeds from asset sales, leaving institutions with less capital for reinvestment or meeting obligations. This can constrain liquidity, forcing adjustments in investment strategies and risk management.
What is the 'lock-in' effect, and why is it important?▼The 'lock-in' effect refers to investors' reluctance to sell appreciated assets to avoid immediate higher tax liabilities. This can reduce market liquidity, decrease the supply of available assets, and potentially increase market volatility over time.
How are institutions preparing for these tax adjustments?▼Institutions are preparing through portfolio restructuring, enhanced tax-loss harvesting, investing in tax-efficient vehicles, upgrading systems for compliance, and engaging with tax experts to navigate the new regulatory landscape effectively.
What are the long-term economic implications of these tax policies?▼Long-term implications include potential impacts on capital formation, market efficiency, and US international competitiveness. A balance must be struck between fiscal goals and maintaining a vibrant investment environment to ensure sustainable economic growth.
Conclusion
The impending 2026 capital gains tax policy adjustments represent a pivotal moment for institutional investors and the broader financial markets. The changes, ranging from higher tax rates to altered definitions of capital gains, will undeniably reshape institutional liquidity, drive significant asset reallocation, and introduce substantial operational challenges. While the primary aim may be revenue generation and wealth redistribution, the ripple effects on investment behavior, market stability, and global competitiveness cannot be underestimated. Institutions that proactively understand, model, and strategically adapt to this evolving tax landscape will be best positioned to mitigate risks and uncover new opportunities, ensuring continued financial health in a complex regulatory environment.
